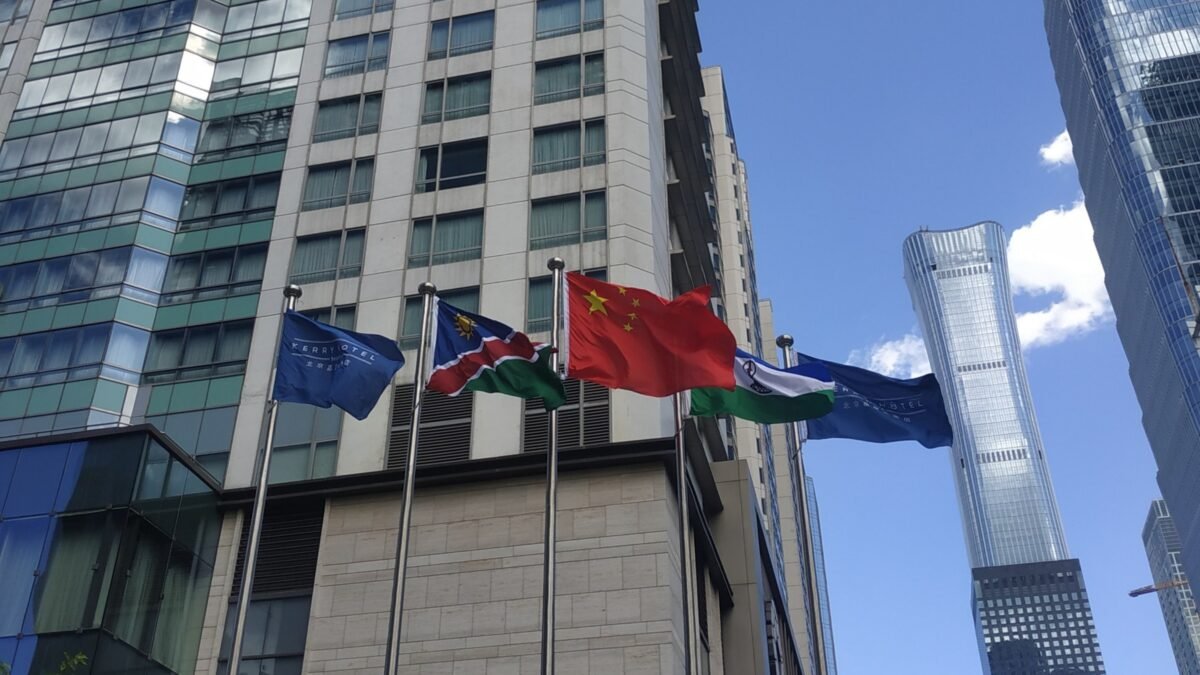
The Forum on China-Africa Cooperation that convened in Beijing in September 2024 was the ninth iteration of a gathering that has reshaped the material infrastructure of the continent more thoroughly than any other bilateral partnership since the end of the Cold War. China’s accumulated investment in Africa, ports, railways, roads, data centres, power plants, represents a physical imprint on governance capacity, trade logistics, and sovereign debt obligations that no set of diplomatic communiqués can obscure. What the 2024 summit revealed is that both sides understand this, and both sides are managing the consequences of a relationship that has passed the point where its terms can be described without acknowledging its asymmetries.
The headline figures from this summit carried a familiar architecture. China committed to extending credit lines, supporting agricultural development, and increasing African exports to the Chinese market. African heads of state arrived with investment lists and sovereign priorities. The language of mutual benefit, South-South cooperation, development without conditionality, shared destiny, remained the rhetorical frame. But beneath that frame, a set of structural questions that the forum format does not easily accommodate were pressing harder than in previous summits.
The Debt Asymmetry
African sovereign debt owed to Chinese institutions has become, over the past decade, one of the defining variables in continental fiscal policy. Countries including Zambia, Angola, Ethiopia, and Kenya carry Chinese debt at levels that constrain their domestic fiscal choices, their ability to access other capital markets, and in some cases their infrastructure governance, ports and rail lines built with Chinese financing are in some instances operated under commercial arrangements that limit host-country control. The restructuring of Zambia’s debt, which involved long and difficult negotiations with Chinese creditors alongside Western bondholders, demonstrated that Chinese lending does not come with the multilateral frameworks that make restructuring predictable. It comes with bilateral relationships whose terms are often opaque.
That opacity is itself a form of leverage, and it is worth naming as one. A multilateral creditor lends inside published rules that bind it as much as the borrower. A bilateral creditor lending under confidential terms keeps the rulebook in its own drawer. When repayment falters, the borrower must negotiate not against a framework but against a relationship, and a relationship can be made to carry conditions, on a port concession, a voting alignment, a resource offtake, that no public covenant would survive. The debt is denominated in money. It is repaid, increasingly, in sovereignty.
What the Infrastructure Delivered
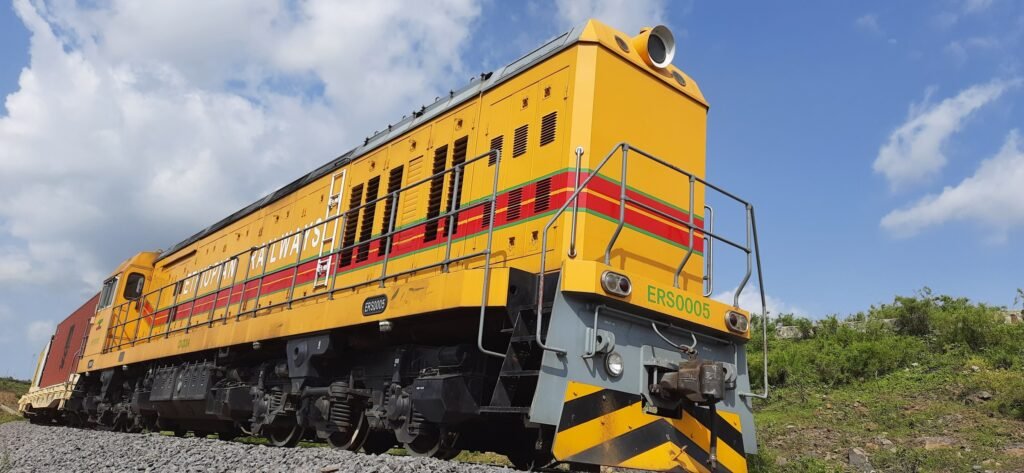
At the same time, dismissing China’s role in African development as predatory misses what the relationship actually delivered. The port at Bagamoyo in Tanzania, the Standard Gauge Railway in Kenya, the roads across Ethiopia and Rwanda, the data centres now powering financial services across East and West Africa, these are not abstractions. They are physical infrastructure that was not built by Western development finance institutions that were available during the same period. The question is not whether Chinese investment added value to African economies. The question is at what price, under what governance terms, and with what long-term implications for sovereign economic control.
The counterfactual is the part Western critique rarely survives. For two decades African finance ministers took Chinese terms not out of naivety but because the alternative on offer was, for most of that period, nothing, or capital wrapped in procurement rules and policy conditions that priced itself out of consideration. A hard bargain accepted against no bargain is not evidence of deception. It is evidence of a vacuum, and the infrastructure competition now underway exists precisely because that vacuum has finally become strategically embarrassing to the powers that left it open.
Leverage, If Organised
The 2024 summit occurred inside a geopolitical context that the 2006 and 2015 summits did not face in the same form. The United States has deployed its own infrastructure initiative, the Partnership for Global Infrastructure and Investment, explicitly to compete with China in African markets. The European Union’s Global Gateway scheme carries similar intent. African governments now sit, for the first time since the Cold War, at the centre of a genuine competition for their alignment and their markets. That competition gives African states negotiating leverage they have not previously held. Whether African leaders are deploying that leverage collectively, through the AU, through regional bodies, through coordinated debt restructuring demands, or individually, in bilateral negotiations where the structural power differential remains significant, is the question that the 2024 summit could not resolve.
That question answers itself badly when fifty-four states bargain one at a time. A single African economy facing Beijing, Washington, and Brussels separately is a price-taker negotiating against price-setters. The same fifty-four coordinating a common floor, on debt transparency, local content, technology transfer, would convert a competition for Africa into a competition on Africa’s terms. The leverage exists in the aggregate and evaporates in the particular, which is precisely why the continental body that could organise it remains weaker than the sum of the bilateral deals that bypass it. A bundle of sticks is hard to break; a single stick snaps, and the creditors have long understood which one they prefer to face.
What emerges from the 2024 China-Africa Summit is a relationship at a threshold. The infrastructure phase, in which the primary mechanism of China’s engagement was construction finance, is maturing into something more complex, a phase in which trade terms, technology transfer, digital infrastructure ownership, and debt sustainability are the operative questions. Africa enters that phase with significant leverage it did not have twenty years ago. Whether it exits that phase with structural economic gains or structural dependency extended into new domains will depend on decisions being made now about how that leverage is organised and applied.