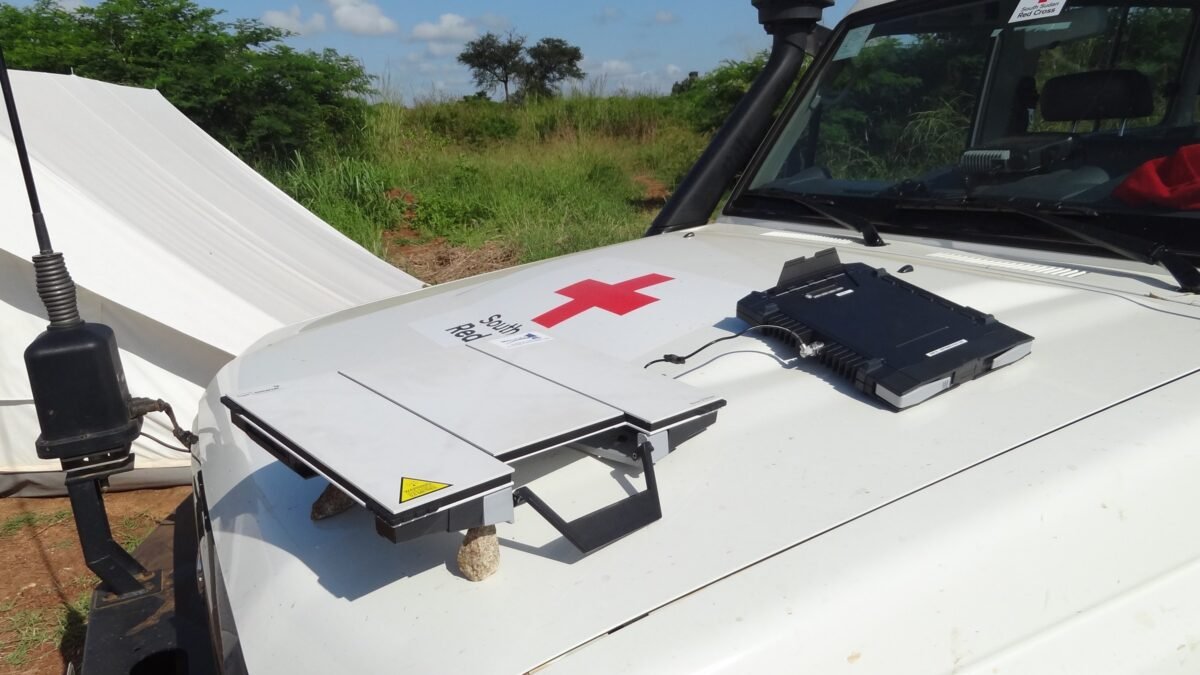
A rural clinic in a district that no fibre line and no cell tower has ever reached can now, in a growing number of African countries, be online within an hour of a technician mounting a small dish and a router. Starlink’s low-earth-orbit satellite network has done something terrestrial telecom infrastructure spent decades and billions of dollars failing to do consistently across the continent’s most remote geography: deliver broadband to places genuinely disconnected from the grid of towers and cables that defines conventional connectivity. The achievement is real and, for the clinics, schools, and households it reaches, transformative. It has also arrived faster than the regulatory frameworks built to govern who controls telecommunications infrastructure inside a sovereign country, and the mismatch is the actual story.
A Network With No Local Infrastructure to License
Conventional telecom regulation in Africa, as elsewhere, was built around a simple point of leverage: a company that wants to operate a network needs spectrum licences, needs to build or lease physical towers and cables inside the country, and needs local ownership or partnership structures that most African telecom laws require in some form. That physical presence gave regulators something to hold, tax, and, if necessary, restrict. Starlink inverts the model. The infrastructure that matters, the satellite constellation, sits in orbit, outside any single country’s jurisdiction, and the ground equipment is a mass-produced consumer terminal a household can order and self-install. A government that wants to regulate Starlink the way it regulates a domestic mobile operator finds there is very little terrestrial infrastructure inside its borders to regulate in the first place.
South Africa’s dispute with Starlink illustrates the tension directly. The company has resisted entering the South African market under the country’s existing ownership requirements, which mandate a minimum local Black ownership stake for telecom licence holders as part of the country’s broad-based economic empowerment framework, a policy with its own legitimate domestic rationale rooted in redressing apartheid-era exclusion. Zimbabwe, Cameroon, and several other states have at various points restricted or delayed Starlink’s licensing over similar sovereignty and security concerns. At the same time, neighbouring countries have approved it and, in some cases, seen users in the restricting country access the service anyway through cross-border equipment purchases, a leakage that regulation aimed at a physical network was never designed to prevent.
A government that wants to regulate Starlink the way it regulates a domestic operator finds there is very little terrestrial infrastructure inside its borders to regulate.
Coverage and Control Are Pulling Apart
The deeper tension is that satellite connectivity decouples two things telecom policy previously bundled together by necessity: delivering coverage and maintaining sovereign control over the infrastructure that delivers it. A government could previously assume that expanding connectivity meant expanding a network it could licence, tax, and, in an emergency, instruct. Satellite service breaks that assumption. It can reach a population a government has failed to connect for decades while remaining almost entirely outside that government’s regulatory or fiscal reach, a genuinely new category of infrastructure dependency that existing law was not written to anticipate.
None of this is an argument for blocking the technology, which is closing a connectivity gap terrestrial operators have had thirty years and considerable subsidy to close and largely have not. It is an argument that African telecom regulators are now negotiating from a position most have not yet adapted to: a foreign-owned network whose core infrastructure they cannot inspect, tax at the point of origin, or meaningfully restrict without also restricting the connectivity their own citizens want and increasingly obtain by whatever legal or semi-legal route is available.
What Regulation Adapted to Orbit Looks Like
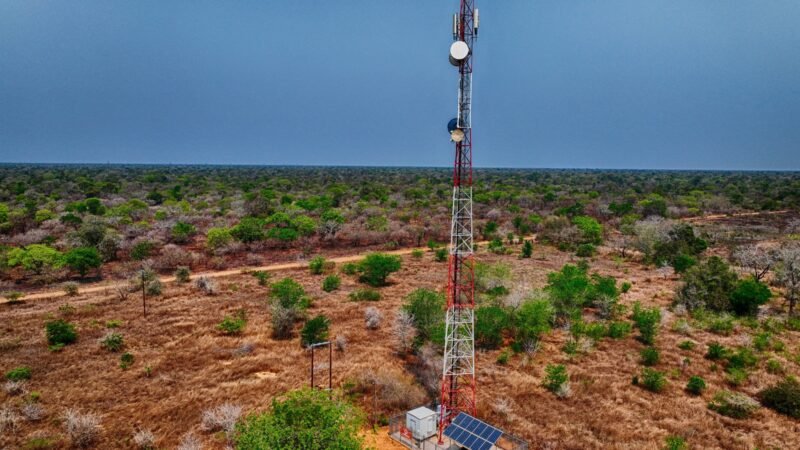
The domestic mobile operators competing against Starlink for the same rural and peri-urban customers face a genuine competitive asymmetry worth naming. An MTN or Safaricom that builds a tower pays spectrum fees, local taxes, and universal service levies that fund the very rural connectivity that satellite providers can undercut without contributing in the same way. A regulator that lets that asymmetry persist indefinitely is not simply tolerating a new entrant; it is allowing the domestic operators who spent two decades building taxable, accountable infrastructure to be undercut by a competitor carrying a fraction of the same obligations. The fairness question is not incidental to the sovereignty question. They are the same question, viewed from the perspective of the company that has to compete against a satellite with no local balance sheet.
The countries managing this transition most effectively are treating satellite providers as a category requiring new regulatory instruments, spectrum coordination, data-routing requirements, revenue-sharing agreements tied to local usage rather than local infrastructure, rather than trying to force a network with no local towers into a licensing regime built for one that has them. Nigeria’s approach, granting Starlink a licence while requiring data localisation commitments and coordination with the national spectrum regulator, is one attempt at that adaptation. Whether it holds up as usage scales, and whether it protects the domestic operators who built the infrastructure the satellite network is now competing against, is the test the next several years will actually run. Coverage arrived ahead of the rulebook. The rulebook is the part still being written.